Maya Torres lost her job in a round of tech layoffs in February, landed a new one in April at a slightly lower salary, and by June had booked a five-day trip to Lisbon she could not comfortably afford. “I kept telling myself the world felt so unstable that I might as well enjoy the money while I had it,” she said. Her rationale is not unusual.
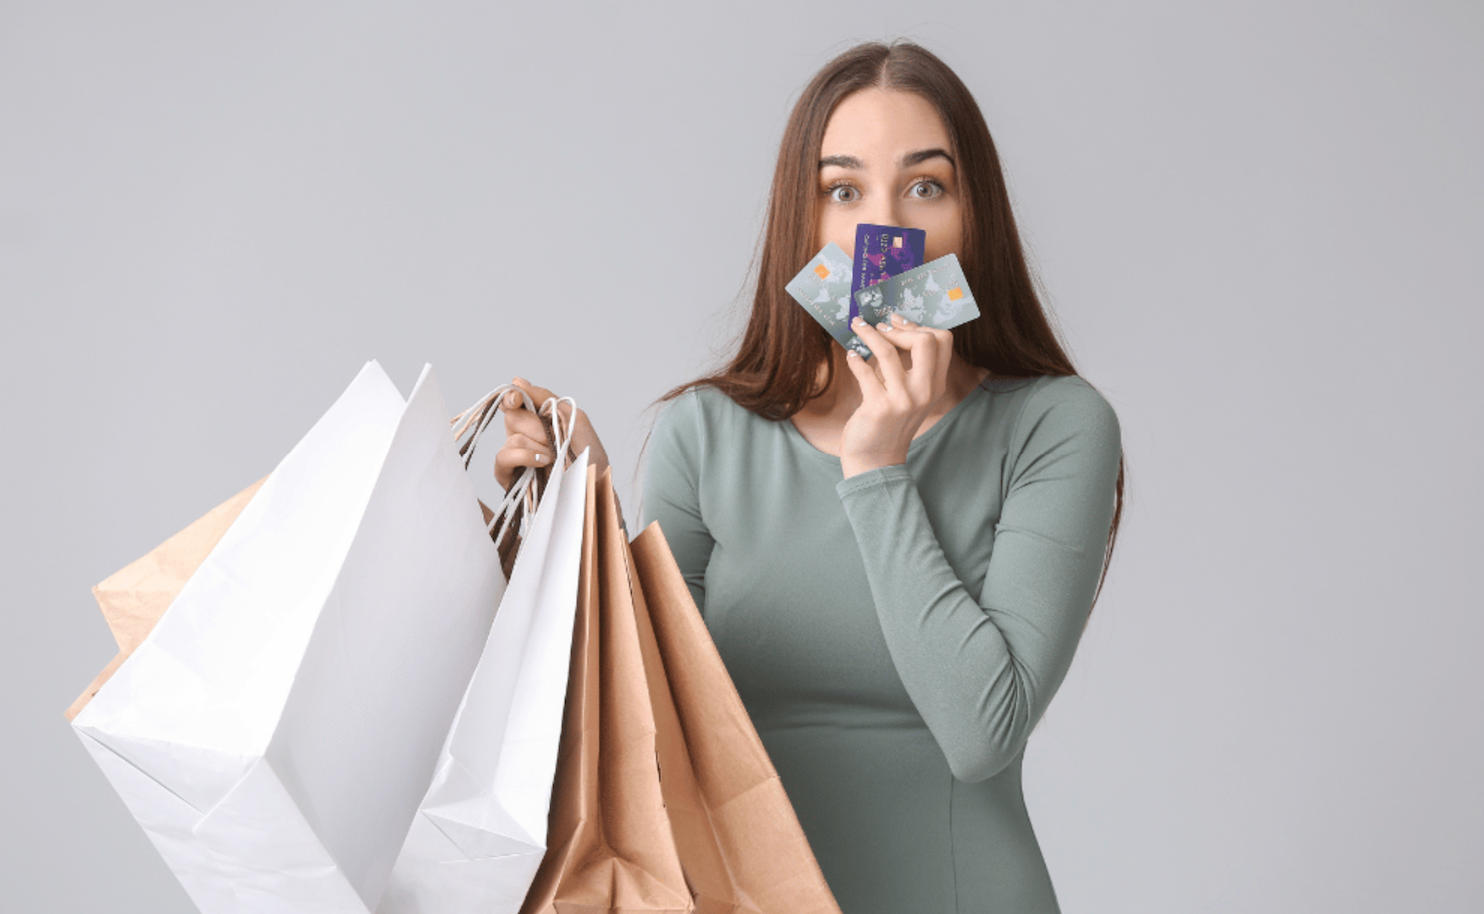
Financial counselors across the country report a wave of clients who describe spending sprees triggered not by confidence in the economy but by dread about it, a pattern now widely labeled doom spending, where uncertainty about the future pushes people toward instant gratification rather than caution.
A Coping Mechanism Disguised as a Shopping Habit
Doom spending sits at the intersection of psychology and economics. Behavioral researchers who study scarcity and stress have long noted that anxiety narrows a person’s time horizon, making the present moment feel far more urgent than any hypothetical future. When headlines cycle through layoffs, inflation, housing costs, and climate disasters, the brain’s reward system starts favoring small, controllable pleasures over long-term planning that feels increasingly out of reach.
- Stress-driven reward seeking: cortisol spikes associated with chronic worry can heighten the appeal of dopamine-triggering purchases, from concert tickets to skincare hauls.
- Learned helplessness: when people feel they cannot influence larger forces like housing prices or job security, they redirect control toward things they can decide in the moment, like a cart at checkout.
- Present bias: psychologists describe a tendency to overvalue immediate rewards relative to future ones, which intensifies under threat.
- Comparison fatigue: constant exposure to other people’s purchases and trips on social feeds can make restraint feel like falling behind rather than getting ahead.
The result is a spending pattern that looks impulsive from the outside but often feels, to the person doing it, like self-preservation. Therapists who work on financial behavior describe clients who can articulate, in precise detail, that a purchase makes no fiscal sense and still complete it minutes later, because the emotional calculation running underneath the decision has little to do with a spreadsheet. The purchase becomes a small proof that the person still has agency over something, even while larger forces feel unmanageable.
This is part of why lectures about budgeting discipline tend to land poorly with people caught in the pattern. Telling someone to simply stop is treating a symptom as though it were the disease. The underlying condition is dread, and dread does not respond well to a spreadsheet.
Social Feeds as an Accelerant
Platforms like TikTok and Instagram have become unlikely partners in this trend. Creators post candid confessions about buying things “because the economy is scary anyway,” turning what might once have been private guilt into a shared joke with millions of views. Hashtags built around doom spending routinely rack up engagement because the format is relatable: a haul video paired with a caption acknowledging that none of it makes financial sense.
This visibility matters. Seeing thousands of strangers admit to the same behavior can normalize it in a way that traditional advertising never could. It also creates a feedback loop, since algorithms tend to serve more of whatever draws engagement, and confessional spending content performs well precisely because it mirrors what viewers are already feeling.
The format itself does some of the persuading. A short video that pairs a self-aware joke with an unboxing sequence delivers permission and temptation in the same fifteen seconds, which is a more efficient persuasion tool than a traditional advertisement ever managed. Viewers are not just watching a purchase; they are watching someone narrate the exact justification they might use themselves, pre-tested for how well it lands with an audience. That rehearsal effect makes the leap from watching to buying shorter than it has been in past consumer cycles, where advertising and purchase were more clearly separated steps.
Comment sections compound the effect further, filling with variations of “I needed this reminder to treat myself,” turning a single creator’s spending choice into a small collective permission slip shared by anyone scrolling past.
Retailers Reading the Mood and Responding
Retail marketing teams have taken notice of the emotional undercurrent driving purchases. Campaigns increasingly lean into comfort, escapism, and small indulgences rather than aspirational luxury. Beauty brands, fast-casual restaurants, and streaming services have all leaned into messaging around treating yourself during hard times, sometimes explicitly referencing economic stress in ad copy.
- Affordable luxury positioning: brands emphasize items priced low enough to justify as an occasional indulgence, like a specialty coffee drink or a mid-tier skincare product.
- Escapism-forward campaigns: travel and entertainment companies market trips and experiences as mental health necessities rather than discretionary spending.
- Limited-time urgency: flash sales and countdown timers exploit the same present-bias tendencies that fuel doom spending in the first place.
Some marketers describe this as meeting customers where they are emotionally. Critics describe it as profiting from a mental health strain that companies did little to cause but plenty to worsen. Internal marketing memos at several consumer brands, reported anecdotally by industry insiders, have reportedly begun referencing “recession indulgence” or “small joy” purchases as a specific customer segment worth targeting with dedicated messaging, a sign that the phenomenon has moved from an observed cultural pattern into a formalized part of campaign planning.
Category performance backs up the strategy from a purely commercial standpoint. Lipstick and inexpensive treat purchases have historically held up during downturns even as bigger-ticket spending falls, a pattern retail analysts sometimes describe informally as the lipstick effect. Doom spending appears to extend that same logic into new categories, including travel bookings, concert tickets, and specialty food delivery, where the ticket price is high enough to feel meaningful but low enough to justify as a coping mechanism.
Financing the Feeling
Doom spending rarely happens with cash sitting idle in a checking account. Much of it runs through credit cards, installment plans, and buy-now-pay-later services that let consumers separate the emotional payoff of a purchase from its financial consequences. Splitting a purchase into four payments can make an impulsive decision feel smaller and more manageable than it is, even when the total cost matches or exceeds what a single upfront payment would have been.
Credit counselors note that this deferred-cost structure compounds the psychological drivers of doom spending. If the goal is momentary relief from anxiety, a financing tool that delays the reckoning offers exactly that relief without forcing an immediate confrontation with affordability. The bill still arrives, but by the time it does, the emotional trigger that prompted the purchase has often faded, leaving behind confusion about why the balance grew so quickly.
- Checkout-stage financing prompts: many online retailers now surface installment options directly at checkout, lowering the perceived cost of a purchase at the exact moment a shopper is deciding.
- Multiple simultaneous plans: consumers juggling several installment agreements across different retailers can lose track of total monthly obligations, since each plan is billed separately and rarely aggregated in one view.
- Credit score entanglement: missed installment payments can affect credit reporting in ways that many shoppers underestimate when they first sign up for the service.
This financing layer transforms doom spending from an occasional emotional lapse into a structural feature of how anxious consumers manage cash flow, stretching the consequences of a single bad week across months of recurring payments.
Who Is Doing the Spending
Doom spending is not confined to any single income bracket or generation, but its expression varies. Younger consumers, especially those early in their careers and carrying student debt, describe it as a rebellion against a financial rulebook that never seemed to guarantee stability anyway. Older consumers closer to retirement describe a different flavor: a sense that decades of careful saving did not insulate them from market volatility, so smaller indulgences feel earned.
- Early-career workers: often cite job insecurity and the feeling that traditional milestones like homeownership are out of reach regardless of saving discipline.
- Parents managing rising costs: report spending on convenience and comfort items as a release valve against the mental load of budgeting for childcare and groceries.
- Near-retirees: describe reduced faith that delayed gratification pays off, especially after watching retirement accounts swing during periods of market turbulence.
A quieter subset worth noting is dual-income households who look financially stable from the outside but describe the same underlying anxiety once housing costs and debt obligations are factored in. Their doom spending tends to be less visible, showing up in slightly nicer everyday purchases, an upgraded grocery order or a spontaneous weekend hotel stay, rather than a single dramatic splurge that would draw attention from friends or family.
Reading the Broader Economic Signals
Consumer confidence surveys and retail spending data give economists a way to track this behavior at scale, even when individual purchases look irrational. Analysts watching the gap between how people say they feel about the economy and how much they are spending have noted periods where sentiment drops sharply while spending on nonessential categories holds steady or even rises. That divergence is one of the clearest fingerprints of doom spending, distinguishing it from ordinary consumer confidence.
Retail analysts tracking categories like beauty, quick-service dining, and entertainment subscriptions have pointed to resilience in these areas even during stretches when broader economic indicators looked shaky. That resilience does not necessarily reflect optimism. It often reflects the opposite: a population bracing for worse news and deciding to enjoy small comforts before conditions tighten further.
Economists who study this divergence caution against reading it as evidence that consumers are financially fine simply because spending numbers hold up. A population can be spending steadily while also accumulating debt, depleting savings, and reporting record levels of financial stress in parallel surveys. The spending figures alone tell only part of the story, and treating them as a stand-alone health indicator risks missing the strain building underneath.
Financial Advisors Push Back
Not everyone treats doom spending as harmless venting. Financial planners increasingly encounter clients whose short-term coping habits have created long-term structural problems, from maxed-out credit lines to depleted emergency funds. The advice from this camp tends to be less about shaming the impulse and more about redirecting it toward decisions with less lasting damage.
- Naming the trigger: advisors suggest pausing to identify whether a purchase is solving an actual need or soothing a feeling, which alone can interrupt the automatic pattern.
- Building a designated buffer: setting aside a small, guilt-free spending allowance can satisfy the emotional urge without threatening larger financial goals.
- Automating savings first: moving money into savings before it reaches a checking account removes the temptation at the source rather than relying on willpower after the fact.
- Seeking low-cost counseling: nonprofit credit counseling services offer structured support for people whose spending has outpaced their income.
The tension in this advice is real. Telling someone anxious about the future to simply save more can sound tone-deaf when that same anxiety stems from the sense that saving no longer guarantees security the way it once did. A number of advisors have begun softening their approach as a result, framing conversations around harm reduction rather than strict elimination, since clients who feel judged for the behavior tend to hide it rather than address it openly in future sessions.
Long-Term Financial Consequences of the Pattern
A single doom-spending purchase rarely derails a household budget on its own. The damage tends to accumulate through repetition, each small splurge layering onto the last until a pattern that felt like a series of isolated coping moments has quietly reshaped someone’s entire financial trajectory. Credit counselors describe clients who can point to a specific bad month that started the habit, but who struggle to explain why it never fully stopped once the original trigger passed.
- Delayed savings milestones: money that might have gone toward a retirement contribution or an emergency fund instead funds recurring small purchases, pushing major goals further out with each cycle.
- Compounding interest exposure: balances carried on credit cards used for doom spending accrue interest that can outpace the original value of the purchases themselves within a year or two.
- Reduced financial flexibility: households with less slack in their budget have a harder time absorbing a real emergency, since discretionary spending has already claimed the cushion that would normally cover it.
- Erosion of long-term confidence: some clients report a growing sense of financial fatalism, where the habit itself becomes evidence supporting the original belief that saving does not pay off anyway.
Some financial therapists argue this last point deserves more attention than it typically receives. Doom spending can become self-reinforcing: the anxiety prompts the spending, the spending weakens the financial position, and the weakened position deepens the original anxiety, creating a loop that a single conversation about budgeting rarely interrupts on its own. Breaking that cycle, in their view, requires addressing the emotional driver directly rather than treating the spending as a standalone behavioral problem to be corrected with better tracking tools alone.
Final Thoughts
Doom spending reflects something larger than a personal budgeting failure. It captures how people respond when the usual promises of financial stability, save diligently, work hard, plan ahead, stop feeling reliable.
The purchases themselves are rarely the real story. The real story is a population coping with prolonged uncertainty by claiming small, immediate wins over the delayed and uncertain ones the economy no longer seems to guarantee.
Addressing it will require more than individual budgeting tips; it calls for a broader reckoning with why so many consumers no longer trust that patience pays off, and what it would take to rebuild that trust.
Frequently Asked Questions
Is doom spending the same as impulse buying?
Not exactly. Impulse buying can happen for many reasons, including boredom or opportunity, while doom spending is specifically tied to anxiety about broader economic or personal instability. The purchases often carry an undertone of resignation, as if spending now is a rational response to a future that feels uncertain anyway.
Does doom spending only involve large purchases?
No, it frequently shows up in smaller, recurring choices like takeout orders, beauty products, or subscription upgrades rather than one-time big-ticket items. The cumulative effect of many small purchases can be just as damaging to a budget as a single large one, and often goes unnoticed for longer.
Are certain age groups more prone to it?
Younger adults facing job instability and housing affordability challenges report the behavior often, but it appears across age groups whenever people feel their long-term financial planning is being undermined by forces outside their control. Near-retirees who experienced market volatility also describe similar patterns.
Can doom spending affect credit scores?
Yes, especially when it relies heavily on credit cards or installment financing, since rising balances and missed payments can lower a credit score over time. The gap between when the emotional relief happens and when the bill arrives makes it easy to underestimate the cumulative cost.
Do retailers deliberately encourage doom spending?
Some marketing strategies do lean into comfort and escapism messaging that resonates with anxious consumers, whether or not that is the stated intent. Critics argue this blurs the line between responsive marketing and exploiting a vulnerable emotional state for profit.
What is one practical first step to interrupt the pattern?
Building in a short waiting period, even just overnight, between the urge to purchase and the act of purchasing tends to reduce doom spending by giving the initial anxiety spike time to pass. Pairing that pause with a small preapproved discretionary budget can address the underlying emotional need without derailing broader financial goals.