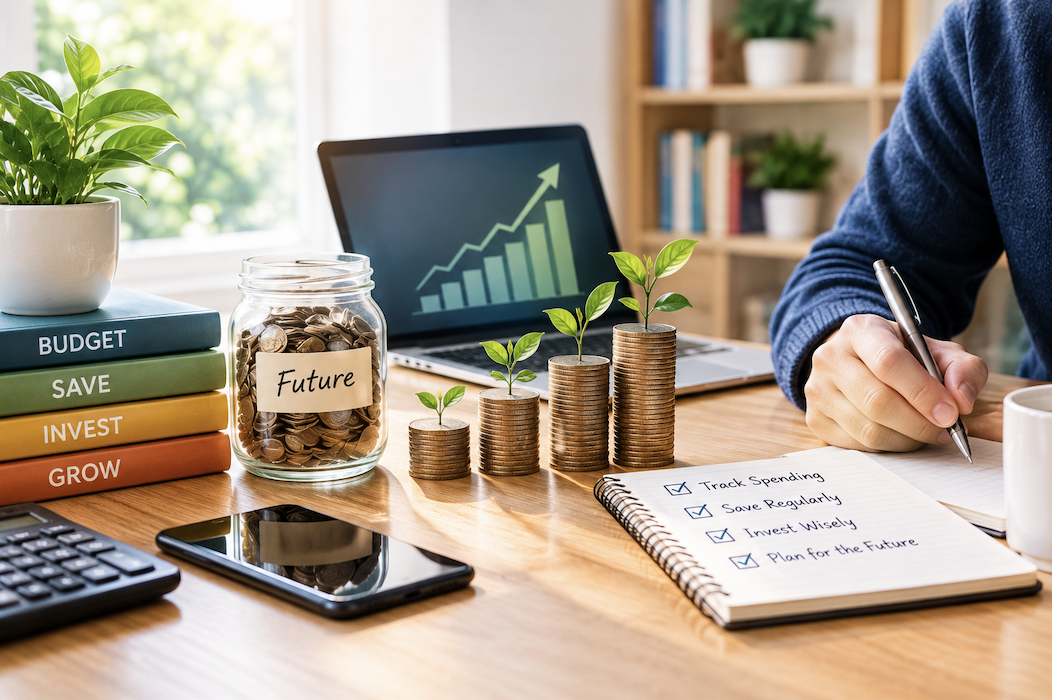
Building real wealth rarely happens through a single lucky break or a dramatic financial decision. It happens through small, consistent habits repeated over years, often so unremarkable that they barely feel worth mentioning. Yet these habits, compounded over time, separate people who reach financial security from those who remain paycheck to paycheck regardless of income level.
Understanding which habits actually matter, rather than chasing the latest trend or shortcut, is the real foundation of long-term financial health.
Spending Less Than You Earn, Consistently
This principle sounds almost too simple to matter, yet it remains the single most important factor in building wealth. Lifestyle inflation, where spending rises alongside income, quietly prevents many people from ever building meaningful savings, even as their salaries grow over the years.
Tracking spending honestly, even informally, reveals patterns that are easy to overlook otherwise. Subscription services, frequent takeout orders, and small impulse purchases often add up to far more than expected once totaled over a month.
Simple Ways to Spend More Intentionally
- Review bank and credit card statements monthly for forgotten subscriptions
- Wait twenty-four hours before making non-essential purchases over a set amount
- Automate savings so money is set aside before it can be spent
- Set a realistic monthly budget rather than an overly restrictive one
Building an Emergency Fund First
Before thinking about investing or aggressive saving goals, having a basic emergency fund protects against the setbacks that can undo years of financial progress. Unexpected car repairs, medical bills, or temporary job loss are far less stressful when a cushion already exists.
Financial experts generally recommend saving three to six months of essential expenses in an easily accessible account. This fund should not be invested in anything volatile, since its purpose is stability and quick access, not growth.
Automating Good Financial Decisions
One of the most effective ways to maintain good financial habits over the long term is to remove the need for constant willpower and decision-making. Automation quietly turns good intentions into consistent action, which matters enormously since motivation naturally fluctuates from month to month.
Setting up automatic transfers to savings and investment accounts on payday, before the money is available to spend elsewhere, is a simple example that consistently outperforms relying on manual discipline alone. Many people find that once these transfers become routine, they barely notice the missing funds, having naturally adjusted spending around what remains available.
- Automate transfers to savings and investment accounts on payday
- Set up automatic bill payments to avoid late fees and credit score damage
- Use separate accounts for different goals to reduce the temptation to overspend
- Review automated systems periodically to ensure they still match current goals
Understanding the Power of Compound Growth
Compound growth is often described as one of the most powerful forces in personal finance, and for good reason. Money invested early has more time to grow, and the returns generated eventually start generating their own returns as well.
This is why starting to invest early, even with small amounts, often outperforms investing larger amounts later in life. Time in the market tends to matter more than trying to perfectly time when to invest.
A Simple Illustration Worth Remembering
Someone who invests a modest amount consistently starting in their twenties will typically end up with significantly more wealth by retirement than someone who invests larger amounts but starts a decade later, purely due to the extra years of compounding.
Diversifying Instead of Chasing Single Bets
Putting all available savings into a single stock, cryptocurrency, or investment opportunity might occasionally produce impressive short-term gains, but it also exposes someone to significant risk of loss. Diversification, spreading investments across different asset types and sectors, helps smooth out volatility over time.
- Consider a mix of stocks, bonds, and other asset classes based on risk tolerance
- Avoid investing money you cannot afford to lose in high-risk assets
- Rebalance investment portfolios periodically rather than leaving them unchecked for years
- Research any investment thoroughly before committing significant funds
Avoiding High-Interest Debt Traps
Credit card debt and other high-interest loans can quietly erode financial progress faster than most saving or investing strategies can offset. Interest charges compound just as investment returns do, except working against the borrower instead of for them.
Prioritizing the repayment of high-interest debt, sometimes even before aggressive investing, often makes more mathematical sense given how quickly interest can accumulate on unpaid balances.
Practical Debt Reduction Strategies
- List all debts by interest rate, focusing extra payments on the highest rate first
- Avoid taking on new high-interest debt while paying down existing balances
- Consider balance transfer or consolidation options where genuinely beneficial
- Set a realistic timeline rather than expecting overnight results
Reviewing and Adjusting Regularly
Personal finance is not a one-time setup but an ongoing process that benefits from regular review. Life circumstances change, incomes shift, and financial goals evolve, all of which may require adjusting a budget, savings rate, or investment strategy.
Setting aside time every few months to review accounts, goals, and progress helps catch problems early and keeps financial habits aligned with actual life circumstances rather than outdated assumptions. This review does not need to be complicated; even a simple checklist covering current savings rate, outstanding debt, and progress toward major goals is often enough to reveal whether adjustments are needed.
- Schedule a brief financial check-in every three to six months
- Review whether your savings rate still matches your current income and goals
- Check that insurance coverage and beneficiaries remain up to date
- Adjust investment allocations if your risk tolerance or timeline has changed
The Psychology Behind Everyday Spending Decisions
Understanding why people overspend often matters as much as knowing the mechanics of budgeting. Many purchasing decisions are driven by emotion rather than logic, whether that means stress shopping after a difficult day, buying something to fit in socially, or making impulse purchases triggered by clever marketing designed to create urgency.
Recognizing these emotional triggers, without judgment, is often the first step toward changing spending patterns that logic alone has failed to fix. Simple strategies, such as pausing before a purchase to ask whether it addresses an actual need or a passing feeling, can interrupt the automatic cycle that leads to regretted spending later.
- Notice emotional states that tend to trigger impulse spending
- Create small, healthier alternatives to reach for during stressful moments
- Unsubscribe from marketing emails that create artificial urgency
- Reflect on past purchases that brought little lasting satisfaction
Understanding the Difference Between Good and Bad Debt
Not all debt is equally harmful, and understanding this distinction helps prevent unnecessary financial stress. Debt used to acquire something that grows in value or increases earning potential, such as a reasonable mortgage or an education loan tied to a genuinely valuable career path, is often considered more strategic than debt used purely for consumption.
Bad debt, on the other hand, typically involves high interest rates attached to depreciating purchases, such as expensive electronics or vacations financed through credit cards. Learning to recognize this difference helps guide better borrowing decisions rather than treating all debt as equally acceptable or equally dangerous.
- Good debt often has lower interest rates and supports long-term value or income
- Bad debt often carries high interest and finances items that lose value quickly
- Even good debt should be manageable relative to income and existing obligations
- Regularly reviewing outstanding debts helps prevent them from quietly accumulating
Protecting Wealth With the Right Insurance
Building wealth is only half the equation; protecting it from unexpected events is just as important. A single uninsured emergency, whether a health crisis, a car accident, or damage to a home, can undo years of careful saving in a matter of weeks without the right coverage in place.
Health insurance, auto insurance, and, depending on circumstances, life or disability insurance act as a financial safety net that prevents a single bad event from becoming a long-term setback. Reviewing existing policies periodically ensures coverage still matches current life circumstances, such as a new home, a growing family, or a change in income.
Insurance Basics Worth Reviewing Annually
- Confirm health insurance coverage still fits current medical needs and budget
- Review auto and home or renters insurance for adequate coverage limits
- Consider disability insurance, especially if income depends heavily on one job
- Reassess life insurance needs after major life changes, such as having children
Setting Realistic Financial Goals
Vague goals like “save more money” rarely lead to lasting change, because there is no clear way to measure progress or know when the goal has been achieved. Specific, measurable goals, such as saving a defined amount for a down payment within a set timeframe, provide direction and make it easier to stay motivated.
Breaking larger goals into smaller monthly targets also makes the process feel more manageable. Someone aiming to save a significant amount within three years, for example, can calculate the required monthly savings and track progress against that specific number rather than feeling overwhelmed by the larger total.
- Define specific, measurable financial goals with clear timeframes
- Break large goals into smaller, trackable monthly milestones
- Revisit and adjust goals as income or circumstances change
- Celebrate meaningful progress to stay motivated along the way
Long-term wealth is built far more often through patience and consistency than through dramatic financial moves. The habits outlined here are neither exciting nor complicated, which is precisely why they work. Anyone willing to apply them steadily over time gives themselves a meaningful advantage over those searching for shortcuts that rarely exist.
Frequently Asked Questions
1. How much should I save each month to build wealth?
A common guideline is saving at least twenty percent of income, though even smaller consistent amounts can build meaningful wealth over time if maintained.
2. Is it better to pay off debt or invest first?
High-interest debt, such as credit cards, is usually worth prioritizing before investing, since the interest owed often exceeds typical investment returns.
3. How much should be in an emergency fund?
Most financial guidance suggests three to six months of essential living expenses, kept in an accessible, low-risk account.
4. Do I need a lot of money to start investing?
No. Many investment platforms allow starting with small amounts, and consistency over time matters more than the initial amount invested.
5. How often should I check my investment portfolio?
Checking every few months is usually sufficient for long-term investors, since frequent checking can lead to emotional decisions based on short-term market fluctuations.
6. Is it too late to start building wealth in my thirties or forties?
No. While starting earlier provides more time for compounding, consistent saving and investing at any age can still build meaningful long-term financial security.